Editorial: The Trump administration's strange affection for prediction markets
Published in Political News
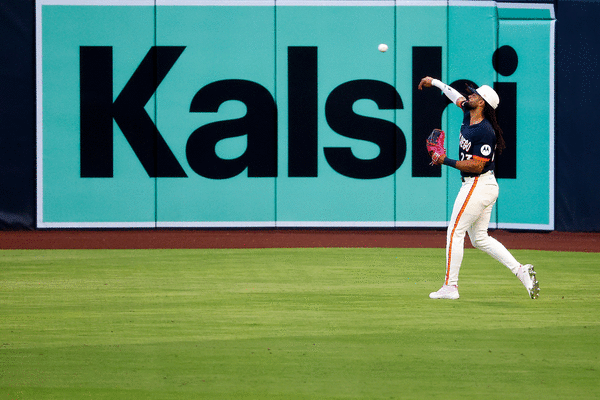
There is something genuinely strange happening at the Commodity Futures Trading Commission, the federal agency responsible for regulating derivatives markets. Under Chairman Michael Selig, the CFTC has challenged states seeking to regulate prediction platforms, arguing that federally designated contract markets fall within its exclusive jurisdiction.
To understand why this dispute matters, let’s return to the original purpose of futures markets. Congress developed the federal framework for commodity futures during the early 20th century partly to stabilize an agricultural economy vulnerable to sharp swings in prices and supply. A farmer and buyer could agree today on the price of wheat delivered months later, protecting both sides against uncertainty.
Derivatives expanded that principle. A farmer might purchase a contract tied to rainfall or temperature and receive compensation if extreme weather damaged the harvest. The contract served an identifiable economic purpose: transferring and managing risk.
Today’s prediction markets stretch that concept dramatically. Federally regulated platforms offer yes-or-no contracts on elections, celebrity encounters, natural disasters and, most controversially, sporting events. Customers can trade on which team will win, how many hits a player will record or whether several outcomes will occur together.
If that sounds like sports gambling, and if bundled contracts sound like parlays, you are hardly alone. Yet the CFTC and the platforms distinguish “trading” contracts on a game’s outcome from placing a “bet” with a sportsbook.
Forty-four state attorneys general challenged that reasoning in July, arguing that the CFTC’s proposed approach exceeded its authority and that sports wagering remains subject to state law. The conflict has produced inconsistent court rulings, with some judges accepting federal preemption arguments and others allowing state regulators to proceed. The CFTC has also filed lawsuits challenging state enforcement efforts.
The dispute is difficult to reconcile with the historical purpose of derivatives regulation. What commercial risk is being hedged when someone buys a contract on how many hits Orioles star Gunnar Henderson will record? When sports contracts and multi-outcome combinations dominate a platform’s activity, the distinction between speculation and gambling becomes increasingly semantic.
The political relationships deserve scrutiny as well. Donald Trump Jr. became an adviser to Kalshi and reportedly received approximately $300,000 in equity when the company was valued below $2 billion. Its valuation later rose to $22 billion.
After New York sought to stop Kalshi from offering event contracts, the CFTC invoked emergency authority directing the exchange to continue operating, citing potential disruption to federally regulated markets.
The legal question is whether federal commodities law overrides state gambling regulation. The larger democratic question is whether reclassifying wagers as financial contracts deprives states of their traditional authority to decide how gambling operates within their borders.
Whatever terminology Washington chooses, the underlying transaction remains recognizable: Money is placed on an uncertain outcome, and one side wins while another loses. Calling it a “contract” does not automatically transform its character.
_____
©2026 The Baltimore Sun. Visit at baltimoresun.com. Distributed by Tribune Content Agency, LLC.


Comments