Editorial: Americans rely on deposit insurance. Now is the time to fortify it
Published in Op Eds
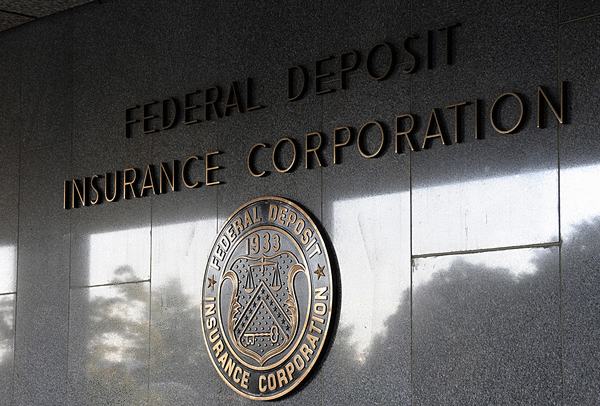
Banks in the U.S. have plenty to celebrate these days, from record profits and higher stock prices to a strong economy and easier regulation. One thing they don’t need is an added discount on their deposit insurance — a crucial buffer that should be reinforced when times are good.
For the better part of a century, U.S. bank customers have been able to rely on the Federal Deposit Insurance Corp. to guarantee their deposits. Banks pay a premium into the FDIC’s reserve, with the largest and riskiest contributing the most. When the reserve falls below its statutory minimum, as during COVID-19 or after the 2023 bank failures, the FDIC demands higher payments or special assessments. With the fund now at its highest in decades, the FDIC has proposed easing the requirements.
Its proposal has three parts. One is sensible: raising the asset threshold between “small” and “large” banks to $30 billion from the $10 billion set two decades ago. But it’s harder to justify the other two elements: Small banks will get a two-basis-point cut in the base rates used to calculate their required payments; large banks, meanwhile, will each get a one-point cut, with a second reduction contingent on their ability to provide the FDIC access to their critical data and systems.
The reasoning is clear: With the fund replenished, banks should be allowed to keep more of their money to use for loans and other economically useful purposes. And with better data, the FDIC might be able to forestall the kind of struggles it faced in managing Silicon Valley Bank’s failure in 2023.
Yet the proposal has two main weaknesses.
One is data security. Although banks take cyber-risks seriously, the same can’t always be said of their overseers. A breach at the Office of the Comptroller of the Currency disclosed last year — which allowed perpetrators to access tens of thousands of emails, some of which included highly sensitive supervisory data — prompted several big banks to stop sharing information with the regulator. A report last month by the FDIC’s inspector general found significant weaknesses in the agency’s incident detection and response capabilities. Other federal regulators have long faced similar problems.
If the FDIC goes forward with this proposal, it would be wise to pause any data-access requirements until it can convincingly strengthen its own defenses and create a system architecture that will minimize risk and address the banks’ concerns.
Yet there’s a second, bigger worry that should make the FDIC rethink the broader proposal. The 2023 bank failures demonstrated the speed at which deposits can be withdrawn, a danger that’s poised to accelerate with the arrival of new technologies such as stablecoins and agentic AI. Rising bond yields, geopolitical conflict and high levels of leverage add to the precarious climate. Regulators, meanwhile, are expediting new bank charters, streamlining access to deposit insurance and reducing capital requirements.
All told, it’s a bad moment to reduce the insurance fund’s firepower. With so many risks on the horizon — and with banks doing well, and thus in a position to afford the premiums — the agency should scrap this proposal and stick with the current assessment rates. After all, once the fund exceeds the agency’s designated reserve ratio of 2% of insured deposits, rate reductions would kick in automatically.
The goal should be to ensure that the fund can handle bank failures without demanding higher contributions in a crisis, when the industry can least afford them. As a former president once said: “The time to repair the roof is when the sun is shining.”
____
The Editorial Board publishes the views of the editors across a range of national and global affairs.
©2026 Bloomberg L.P. Visit bloomberg.com/opinion. Distributed by Tribune Content Agency, LLC.



Comments